Buying a home, step by step.
Whether this is your first home or your next one, we will explain each step, help you get organized, and keep you updated from the first conversation to the closing table.
From first conversation to closing.
Here is what to expect. Every purchase is a little different, and we will tailor each step to you. Learn more about home purchase loans and refinancing.
- 1
Start a conversation
Tell us what you are hoping to buy, your timeline, and any questions. We will talk through your budget and the loan options that may fit. No pressure and no commitment.
- 2
Get prequalified or preapproved
We review your information, and for a preapproval we check credit and verify income and assets. A preapproval letter shows sellers you have done your homework.
- 3
Shop with your agent
With a price range in mind, you and your real estate agent look for the right home. We are here for quick questions about payments or costs along the way.
- 4
Make an offer and apply
Once your offer is accepted, we complete your full application, send your Loan Estimate, and give you a list of any remaining documents.
- 5
Appraisal and underwriting
The home is appraised, title work begins, and underwriting reviews your file. We keep you and your agent updated and let you know right away if anything else is needed.
- 6
Closing day
You review your Closing Disclosure ahead of time, sign your final documents, and get your keys. We will walk you through what to bring and what to expect.
Document checklist.
These are the documents lenders commonly ask for. Check them off as you gather them. Your list may be shorter or longer depending on your loan, and we will tell you exactly what you need.
Income
Assets
Identity & history
Once you are under contract
Tip: send complete statements with every page, even blank ones, and avoid moving money between accounts while your loan is in process.
New to this? Start here.
Buying your first home comes with a lot of new terms. These four steps will help you feel ready.
Know your comfortable payment
Think in monthly terms, including taxes, insurance, and any HOA dues, not just the purchase price.
Check your credit early
Review your reports for free at AnnualCreditReport.com and keep paying every bill on time.
Plan for more than the down payment
Budget for closing costs, moving, and a cushion of savings after you move in.
Ask about assistance
Down payment and closing cost assistance programs may be available in Texas. Ask us what you may qualify for.
Questions we hear every week.
Don't see yours? Ask us. No question is too basic.
How much do I need for a down payment?
What credit score do I need?
How long does the process take?
What is the difference between prequalification and preapproval?
Will talking with you affect my credit?
Can I buy a home if I am self-employed?
Homes our clients now call home.
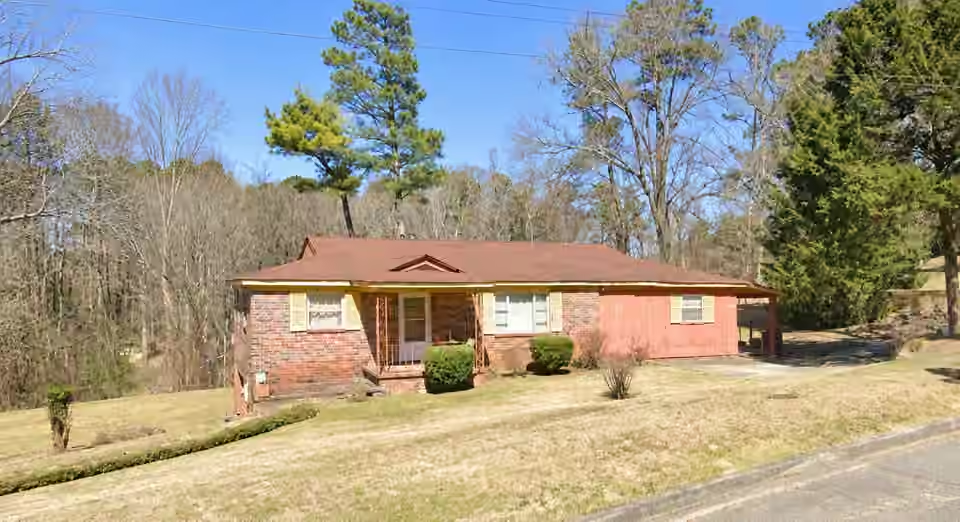 Closed & funded
 Closed & funded
 Closed & funded
 Closed & funded
Ready to take the first step?
Start with a no-pressure conversation with Chad or Rachel.
